Short answer: what does homeowners insurance cover? A standard policy protects four things — the structure of your home (dwelling coverage), detached structures like a shed or garage, your belongings (personal property), and your financial liability if someone is hurt on your property or you damage someone else’s. It also pays for a hotel and meals if a covered loss makes your home temporarily unlivable. What it does not cover is just as important: flood, earthquake, and routine maintenance problems are excluded from nearly every standard policy.
Most homeowners buy a policy, file it away, and never actually read what’s in it until they need to file a claim — which is exactly the wrong time to discover a gap. Understanding what does homeowners insurance cover before disaster strikes is the difference between a claim that goes smoothly and a five-figure bill you’re left holding yourself.
This guide breaks down each piece of a standard HO-3 policy — the type roughly three out of four U.S. homeowners carry — what it pays for, typical coverage limits, the exclusions that catch people off guard, and how to figure out how much coverage you actually need.
What Does Homeowners Insurance Cover? An Overview of the Four Main Protections
A standard homeowners policy bundles four separate coverages into one annual premium: dwelling coverage for the structure itself, personal property coverage for your belongings, liability coverage if you’re responsible for someone else’s injury or property damage, and loss of use coverage for temporary living expenses. Most policies also include a small amount of medical payments coverage and a separate, smaller limit for structures not attached to the house. Each coverage has its own dollar limit, and they don’t share a pool — exhausting your personal property limit doesn’t reduce what’s available for dwelling repairs.
Dwelling Coverage: Protecting Your Home’s Structure
Dwelling coverage pays to repair or rebuild the physical structure of your home — walls, roof, floors, built-in cabinets, and permanently attached fixtures — after a covered loss like fire, wind, or a burst pipe. The number that matters here is replacement cost, not market value.
Replacement cost reflects what it would actually cost to rebuild your home at today’s labor and material prices, which is often higher than what the home would sell for, especially since land value isn’t part of the calculation. Insuring to market value instead of replacement cost is one of the most common — and most expensive — mistakes homeowners make when they’re figuring out what does homeowners insurance cover and how much of it they actually need.
Other Structures Coverage
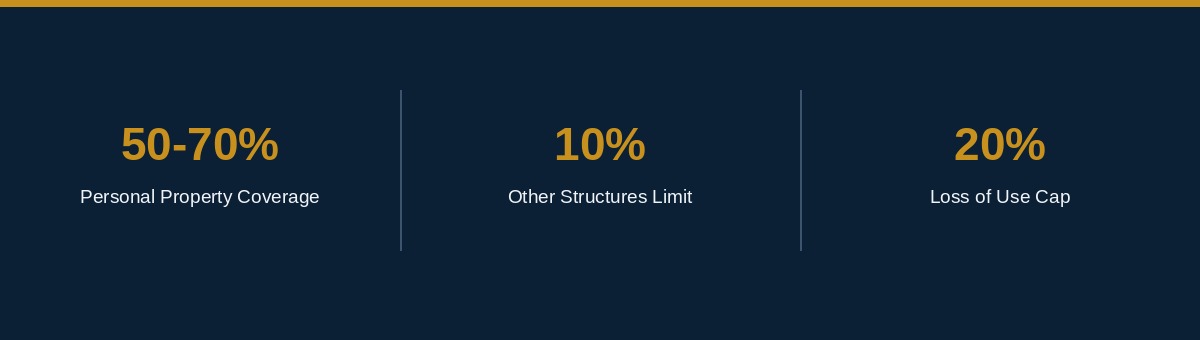
Detached structures on your property — a shed, a detached garage, a fence, or a gazebo — are covered under a separate “other structures” limit, typically set at around 10% of your dwelling coverage. If your dwelling coverage is $300,000, that usually means roughly $30,000 available for detached structures. This limit is easy to overlook until a storm takes out a fence or a detached garage, so it’s worth checking that 10% actually covers what you have on the property — it’s a small but easy-to-miss piece of what does homeowners insurance cover.
Personal Property Coverage: What Happens to Your Belongings
Personal property coverage pays to repair or replace your belongings — furniture, clothing, electronics, appliances — after a covered loss, and it’s typically set at 50% to 70% of your dwelling coverage. On a $300,000-insured home, that works out to roughly $150,000 to $210,000 in contents protection. High-value items like jewelry, fine art, and collectibles usually face sub-limits of $1,000 to $2,500 unless you add a scheduled personal property rider, so it’s worth inventorying anything expensive and confirming it’s actually covered at full value.
Loss of Use and Additional Living Expenses
If a covered loss makes your home temporarily uninhabitable, loss of use coverage — sometimes called additional living expenses — pays for a hotel, temporary rental, and extra meal costs while repairs are underway. Most policies cap this benefit at roughly 20% of dwelling coverage, which on a $300,000 policy works out to about $60,000. It’s one of the more overlooked pieces of what does homeowners insurance cover, since most people never think about it until they’re standing outside a house that just caught fire.
Personal Liability and Medical Payments
Liability coverage protects you financially if you’re found responsible for someone else’s injury or property damage — a guest who slips on your icy driveway, or a tree on your property that falls on a neighbor’s fence. Standard policies usually start at $100,000 in liability protection, and it covers legal defense costs in addition to any settlement or judgment — a core part of what does homeowners insurance cover that many buyers underestimate.
Medical payments coverage, typically $1,000 to $5,000, is separate and pays a guest’s minor medical bills after an injury on your property regardless of who was at fault, which usually keeps small incidents from turning into lawsuits.
What Homeowners Insurance Does Not Cover
Knowing what does homeowners insurance cover also means knowing what it doesn’t. Standard policies explicitly exclude flood damage and earthquake damage — both require separate coverage, flood through the National Flood Insurance Program or a private carrier, and earthquake through a state-specific endorsement. Sewer and drain backups are also excluded unless you add a specific endorsement, which is inexpensive relative to the cost of a backed-up sewer line.
Damage from neglect, gradual deterioration, mold caused by a slow undetected leak, and pest infestations are excluded across nearly every standard policy, because insurance is designed to cover sudden, accidental losses, not the cost of routine home maintenance.
How Much Coverage Do You Actually Need?
Start with a replacement-cost estimate from your insurer or an independent appraiser, not your home’s purchase price or Zillow estimate. From there, check that personal property, other structures, and loss-of-use limits are all proportional to that dwelling number using the percentages above, and raise liability coverage — often to $300,000 or $500,000, or add an umbrella policy — if you have significant assets to protect. Anyone in a flood zone or earthquake-prone area should treat those add-on policies as close to mandatory, not optional, regardless of what a standard homeowners policy already includes.
Frequently Asked Questions
What does homeowners insurance cover that renters insurance doesn’t?
Homeowners insurance covers the physical structure of the home (dwelling and other structures) in addition to personal property and liability. Renters insurance only covers personal property, liability, and loss of use, since the landlord’s policy covers the building itself.
Does homeowners insurance cover water damage?
Sudden, accidental water damage — like a burst pipe — is typically covered. Gradual leaks, flooding from outside the home, and sewer backups generally are not, unless you’ve added a specific endorsement.
Is homeowners insurance required by law?
Understanding what does homeowners insurance cover doesn’t answer whether it’s mandatory: no state requires you to carry homeowners insurance, but any mortgage lender will require it as a condition of the loan for as long as you’re paying off the mortgage.
How often should I review my coverage limits?
Review your policy every year at renewal, and immediately after any major purchase, renovation, or home improvement project, since your dwelling and personal property limits need to keep pace with what you’d actually need to rebuild and replace.
Bottom Line on What Does Homeowners Insurance Cover
What does homeowners insurance cover, in one sentence: your home’s structure, your belongings, your liability if someone gets hurt, and your temporary living costs if you’re displaced — with flood, earthquake, and routine maintenance problems carved out as the major exclusions. Reading your declarations page once a year and matching your limits to your home’s actual replacement cost is a 20-minute task that can save you tens of thousands of dollars the one time you actually need to file a claim.
For more on how coverage limits and premiums actually work, the Insurance Information Institute’s guide to homeowners coverage limits is a solid independent reference to check your numbers against.
Related Reading
Renters Insurance 101: What It Covers and Why You Need It
Lower Your Car Insurance Premium and Save Big: The Proven 2026 Guide

About the Author: BizShieldGuide Team
The BizShieldGuide team researches and writes plain-language guides to business and personal insurance — general liability, professional liability, workers' compensation, business owners policies, cyber liability, and industry-specific coverage for small business owners, alongside straightforward explainers on auto, home, and renters insurance for everyday readers. Our articles are grounded in publicly available data from insurers and carriers (Insureon, The Hartford, Progressive, State Farm, and others), industry cost surveys, and standard policy language, and we link to primary sources wherever a number or coverage detail could change. We are not licensed insurance agents or brokers, and nothing here replaces a quote or advice from one for your specific situation.