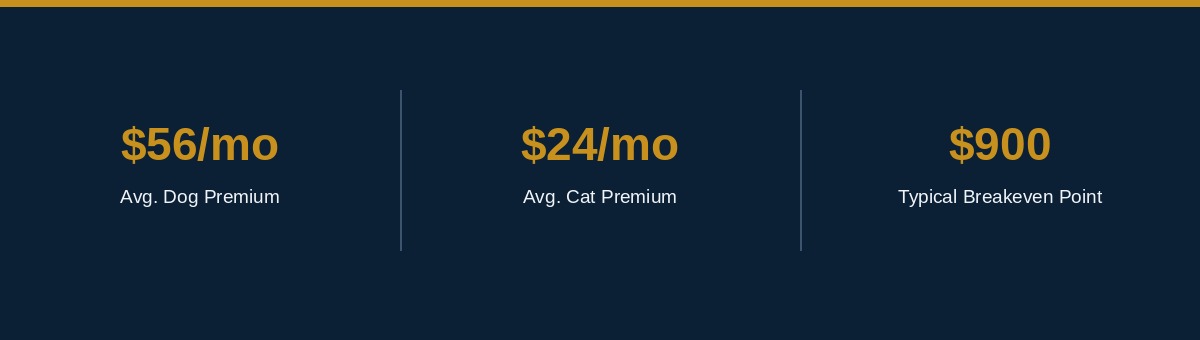
Short answer: is pet insurance worth it? For most pet owners, yes — but only if you buy it while your pet is young and healthy, and only if you’d struggle to pay a surprise $3,000-$8,000 vet bill in cash. A typical dog policy runs $56 a month for $5,000 in annual coverage, and it breaks even the moment your pet needs more than about $900 in vet care in a single year, which happens more often than owners expect.
The honest version of is pet insurance worth it isn’t a flat yes or no — it depends heavily on your pet’s breed, age, and your own risk tolerance. A healthy two-year-old cat with no history of illness is a very different bet than an eight-year-old large-breed dog prone to joint problems.
This guide breaks down what pet insurance actually costs in 2026, how deductibles and reimbursement percentages work, what’s covered and excluded, a real breakeven calculation, and how to decide whether buying a policy or self-insuring makes more sense for your specific pet.
Is Pet Insurance Worth It? What It Actually Costs in 2026
Average monthly premiums for dogs range from about $56 for a $5,000 annual coverage plan up to $87 for unlimited coverage. Cats are cheaper — roughly $24 to $37 a month for the same range of plans. Age matters more than almost anything else: a puppy averages around $43 a month, while a 7-year-old dog averages closer to $74, since older pets are statistically more likely to need care.
How Deductibles and Reimbursement Actually Work
Most policies use an annual deductible, typically $250 to $750, that you pay out of pocket before coverage kicks in for the year. After that, the insurer reimburses a set percentage of each eligible bill — usually 70%, 80%, or 90% — up to an annual maximum that ranges from $5,000 to unlimited.
Here’s what that looks like on an actual bill: an $800 emergency surgery, an 80% reimbursement plan, and a $250 deductible already met for the year means the insurer pays $440 (80% of the remaining $550), and you’re out $360 instead of the full $800.
What’s Covered and What’s Excluded
Part of answering is pet insurance worth it means knowing exactly what you’re buying. Standard accident-and-illness plans cover injuries, illnesses, surgeries, diagnostic tests, and prescription medications. Wellness add-ons — often a separate, cheaper rider — cover routine vaccines and checkups, but most owners skip these since routine costs are predictable enough to budget for directly. Every pet insurer excludes pre-existing conditions, meaning anything your pet was already showing symptoms of before the policy started, and many plans exclude or limit coverage for breed-specific hereditary conditions like hip dysplasia in large dogs.
The Breakeven Math: When Does Pet Insurance Actually Pay Off?
Is pet insurance worth it in dollar terms? Take a $56-a-month dog policy — that’s $672 a year in premiums. With an 80% reimbursement rate and a $250 deductible, you break even the moment your annual vet bills exceed roughly $900. Multiple studies of vet insurance claims show that a single emergency visit averages $1,500 to $5,000, and a serious surgery or cancer treatment can run well past $10,000, which is exactly the scenario pet insurance is designed to protect against.
Should You Self-Insure Instead?
Self-insuring — putting your would-be premium into a dedicated savings account every month — can work for a young, healthy pet from a low-risk breed, especially if you already have an emergency fund that could absorb a large one-time vet bill. The math changes fast with age and breed risk: large-breed dogs, brachycephalic breeds like bulldogs, and any pet with a family history of chronic illness tend to make insurance pay off faster than a self-funded savings account would.
When to Buy: Timing Matters More Than People Think
Is pet insurance worth it depends heavily on timing: the single biggest factor is enrolling before anything goes wrong. Every condition your pet has already been diagnosed with becomes a permanent pre-existing exclusion the moment you apply, so a policy bought at 8 weeks old covers far more than the same policy bought at age 6, after a first vet visit has already flagged a joint or heart issue.
Frequently Asked Questions
Is pet insurance worth it for an older pet?
It’s still worth considering, but premiums rise sharply with age and any existing condition becomes permanently excluded. Older pets are more likely to need care, so even a pricier premium can still pay off — just compare the monthly cost against your pet’s actual health history first.
Does pet insurance cover pre-existing conditions?
No. Every major pet insurer excludes conditions your pet showed symptoms of before the policy’s effective date, which is why buying early — ideally before a pet’s first vet visit — maximizes what a policy actually covers.
What’s a reasonable deductible to choose?
A $250-$500 deductible balances a manageable monthly premium against a reasonable out-of-pocket cost per incident. Higher deductibles lower your premium but mean you’re covering more of a routine claim yourself.
Is pet insurance worth it if my pet is perfectly healthy right now?
Yes, arguably more so — a healthy pet qualifies for the lowest premiums and the fewest exclusions, and you can’t predict an accident like a swallowed object or a car injury, which are among the most common and expensive claims insurers pay.
Bottom Line: Is Pet Insurance Worth It?
Is pet insurance worth it? For most owners, the answer is yes, provided you buy it early, pick a deductible and reimbursement rate you can actually afford, and treat it as protection against a catastrophic bill rather than a way to cover routine checkups. Run the breakeven math against your specific pet’s breed and age, and if the answer is close, buying earlier rather than later is almost always the better bet, since pre-existing exclusions only grow over time.
For an independent breakdown of provider-by-provider pricing, the National Association of Insurance Commissioners’ pet insurance consumer guide is a solid neutral reference to compare against.
Related Reading
Renters Insurance 101: What It Covers and Why You Need It
Term vs Whole Life Insurance: The Proven Way to Save and Choose Right in 2026

About the Author: BizShieldGuide Team
The BizShieldGuide team researches and writes plain-language guides to business and personal insurance — general liability, professional liability, workers' compensation, business owners policies, cyber liability, and industry-specific coverage for small business owners, alongside straightforward explainers on auto, home, and renters insurance for everyday readers. Our articles are grounded in publicly available data from insurers and carriers (Insureon, The Hartford, Progressive, State Farm, and others), industry cost surveys, and standard policy language, and we link to primary sources wherever a number or coverage detail could change. We are not licensed insurance agents or brokers, and nothing here replaces a quote or advice from one for your specific situation.