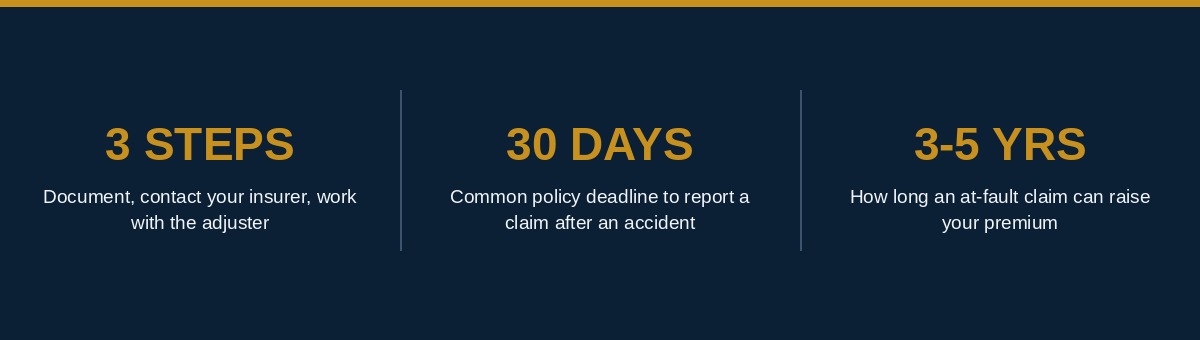
Short answer: to file a car insurance claim after an accident, document the scene first, contact your insurer as soon as possible through their app, portal, or phone line, and then work with the adjuster they assign — most insurers have a policy deadline (often 30 days) for reporting, and starting late is one of the most common reasons a claim gets delayed or denied.
The process itself isn’t complicated, but it’s easy to get wrong in the adrenaline of the moment right after a crash — forgetting to photograph something, giving a recorded statement before you’ve thought it through, or simply waiting too long to report because you weren’t sure the damage was “bad enough” to bother with.
This guide walks through the three real steps to file a car insurance claim, what happens after you submit it, when it’s actually worth filing versus paying out of pocket, and the mistakes that most often slow a claim down or get it denied outright.
Step 1: Document the Scene Before You Do Anything Else
Before you leave the scene (or as soon as it’s safe to do so), photograph the damage to every vehicle involved, the overall accident scene and road conditions, any visible skid marks or debris, and the other driver’s license plate and insurance card. Get the names, phone numbers, and insurance information of everyone involved, plus contact information for any witnesses — witnesses are far easier to reach in the first hour than a week later.
If the accident involves significant damage, injury, or a dispute about fault, call the police and get a report filed — the report number becomes a key piece of documentation your insurer will ask for, and having an official account of the scene matters most in exactly the cases where fault is contested.
Step 2: Contact Your Insurer as Soon as Possible
To file a car insurance claim, report the accident through your insurer’s app, online portal, or claims phone line as soon as you reasonably can — most policies specify a reporting deadline, commonly around 30 days, though it varies by insurer and state, and starting the claim immediately gives the adjuster the freshest version of events to work with. You’ll typically need your policy number, the date, time, and location of the accident, and the information you gathered in step one.
Stick to the facts when describing what happened. You’re not required to speculate about fault, and it’s reasonable to say “I’m still gathering information” rather than guess at details you’re not sure about — a recorded statement becomes part of the permanent claim file.
Step 3: Work With the Claims Adjuster
Once you file, your insurer assigns a claims adjuster who reviews the accident details, may request additional documentation or a vehicle inspection, and ultimately determines fault percentage and payout amount. If the other driver’s insurer disputes fault, their adjuster may also contact you — you’re not obligated to give them a recorded statement, and it’s reasonable to direct them to your own insurer instead.
Keep your own log of every call, email, and document exchanged during this process, including names and dates. If the claim stalls or a decision seems unreasonable, this record is what makes an appeal or escalation to a state insurance department actually go somewhere.
What Happens After You File: A Realistic Timeline
A straightforward claim with clear fault and modest damage can resolve within one to two weeks. A claim involving injury, disputed fault, or a total loss determination can take several weeks to a few months, especially if it requires an independent damage inspection or negotiation over vehicle valuation. Staying in regular contact with your adjuster — a quick check-in call every week or two — tends to keep a claim moving faster than assuming it’ll resolve itself.
Should You File a Car Insurance Claim at All?
Not every fender-bender is worth filing a claim over. If the repair cost is close to or below your deductible, filing may cost you more in future premium increases than it saves — a $600 repair against a $500 deductible nets you $100 from the insurer but can raise your premium by more than that over the following renewal cycles. Get a repair estimate first, compare it honestly against your deductible, and factor in that an at-fault claim typically affects your rate for three to five years before it fully drops off.
At-Fault vs. Not-At-Fault: How the Process Differs
If you’re not at fault, you can generally file against the other driver’s liability coverage instead of your own policy, which usually protects your own premium and doesn’t touch your deductible. This route can take longer, since you’re relying on another insurer’s cooperation, and some drivers choose to file under their own collision coverage first (paying their deductible) and let their insurer pursue reimbursement from the at-fault party’s insurer through subrogation — recovering your deductible once that process completes.
If you are at fault, the claim runs entirely through your own policy’s liability and collision coverage, and it’s this scenario that most directly affects your future premium, since insurers weight at-fault accidents far more heavily than not-at-fault ones when recalculating your rate.
Common Mistakes That Delay or Sink a Claim
When you file a car insurance claim, the most common mistake is waiting too long to report — insurers can deny a claim outright for late reporting if it prevented them from properly investigating. The second is failing to document the scene thoroughly, leaving the claim to come down to your word against the other driver’s. The third is giving a recorded statement to the other driver’s insurance company without first talking to your own — you have no obligation to do this, and it rarely works in your favor.
How Filing a Claim Affects Your Premium
An at-fault claim typically raises your premium at your next renewal and can continue affecting your rate for three to five years, depending on the insurer and state. A not-at-fault claim where you’re reimbursed by the other driver’s insurer usually has little to no effect on your own rate, though some insurers still weigh claim frequency regardless of fault — which is worth asking your agent about directly, since policies on this vary more than most drivers expect.
Frequently Asked Questions
Do I have to file a police report to file an insurance claim?
Not always — for minor accidents with no injury, some states and insurers don’t require one. But a police report strengthens your claim significantly if fault is disputed, so it’s worth calling for anything beyond a trivial parking-lot scrape.
Can my claim be denied?
Yes — common reasons include late reporting, insufficient documentation, a lapsed policy at the time of the accident, or damage that falls under a specific exclusion in your policy. Reading the denial letter closely and appealing with additional documentation resolves many denials.
How long do I have to file a car insurance claim?
It varies by policy and state, but many insurers specify a reporting window of around 30 days from the accident — check your policy’s declarations page for the exact number rather than assuming.
Bottom Line: How to File a Car Insurance Claim
Document everything at the scene, report the accident to your insurer promptly rather than waiting to see how you feel about it, and keep your own paper trail throughout the adjuster process. Whether to file at all often comes down to simple math against your deductible and the multi-year premium impact of an at-fault claim — running that math before you call, not after, is what separates a smooth claim from a costly surprise.
For state-specific rules on claim reporting deadlines and your rights during the process, the National Association of Insurance Commissioners’ auto claims guide is a solid neutral reference.
Related Reading
Lower Your Car Insurance Premium and Save Big: The Proven 2026 Guide
How Does Credit Score Affect Car Insurance Rate? A 2026 Guide

About the Author: BizShieldGuide Team
The BizShieldGuide team researches and writes plain-language guides to business and personal insurance — general liability, professional liability, workers' compensation, business owners policies, cyber liability, and industry-specific coverage for small business owners, alongside straightforward explainers on auto, home, and renters insurance for everyday readers. Our articles are grounded in publicly available data from insurers and carriers (Insureon, The Hartford, Progressive, State Farm, and others), industry cost surveys, and standard policy language, and we link to primary sources wherever a number or coverage detail could change. We are not licensed insurance agents or brokers, and nothing here replaces a quote or advice from one for your specific situation.