Short answer: to figure out how much life insurance you need, most financial guides point to one of a few standard formulas — a simple 10x-your-income rule, an income-plus-education version, or the more detailed DIME method (Debt, Income, Mortgage, Education) — and then adjust the result for your own savings, existing coverage, and family situation.
Quick preview of the answer: how much life insurance do you need depends mostly on income replacement years and any remaining mortgage balance.
None of these formulas is a perfect science, but each gives you a defensible starting number instead of guessing. This guide walks through each method with real numbers, explains when term versus whole life makes sense, and covers the mistakes that lead people to buy too little (or too much) coverage.
Why “How Much Life Insurance Do You Need” Doesn’t Have One Universal Answer
Life insurance exists to replace what you’d otherwise leave behind for the people who depend on your income — which means the right amount is inherently personal, shaped by your income, debts, dependents, and existing savings, not a single number that applies to everyone.
A single 25-year-old with no dependents and no debt has a fundamentally different need than a 40-year-old with a mortgage, two kids, and a spouse who left the workforce to raise them. The formulas below exist to turn that personal situation into a concrete number, and the right approach is usually to run more than one of them and use the range as a sanity check rather than treating any single formula as exact.
Before running any formula, it helps to restate the question plainly: how much life insurance do you need given your specific debts and dependents?
The Four Formulas at a Glance
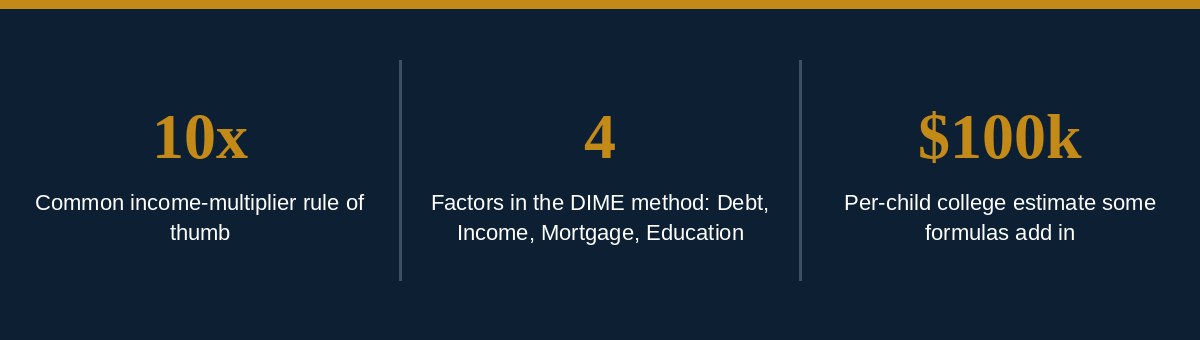
Before going through each method in detail, it helps to see how they compare directly. The 10x income rule is the fastest to calculate and the least precise. The income-plus-education version adds a college estimate for each child, improving accuracy for parents specifically without much added complexity.
The DIME method is the most work to calculate but the most accurate, since it’s built from your actual debts, income, mortgage, and education costs rather than a flat multiplier.
And subtracting existing savings and coverage — a step that applies to whichever formula you use — is what turns a total-obligation estimate into the actual new-coverage number you should be shopping for. Running more than one of these and comparing the results is a reasonable way to sanity-check whichever number you land on, especially if the different methods produce meaningfully different totals.
Most people asking how much life insurance do you need are really asking how to replace their income, not just pick a round number.
Method 1: The 10x Income Rule
The simplest and most commonly cited rule of thumb is to multiply your annual gross income by ten. Someone earning $60,000 a year would target roughly $600,000 in coverage under this method.
It’s popular because it’s easy to calculate and gives a reasonable ballpark for a straightforward household — but it’s also the least precise method here, since it doesn’t account for existing savings, other coverage you may already have, how many dependents rely on that income, or major debts like a mortgage. Treat the 10x rule as a fast starting estimate, not a final number, especially if your situation is more complex than a single-income household with no significant debt.
Method 2: Income Plus Education (10x + College)
A slightly more detailed variation takes the same 10x-income base and adds a flat estimate for each child’s future education costs, commonly figured around $100,000 per child for college.
If you remember nothing else, remember this: how much life insurance do you need is a personal calculation, not a one-size-fits-all rule.
Under this method, someone earning $60,000 with two kids would target roughly $600,000 plus $200,000, or about $800,000 in coverage. This version is a meaningful improvement over the plain 10x rule for parents specifically, since education is one of the largest predictable future expenses a surviving spouse would otherwise have to cover alone — but it still doesn’t account for a mortgage balance, other debts, or existing savings and coverage, which is where the more detailed DIME method comes in.
Method 3: The DIME Method (Most Thorough)
DIME stands for Debt, Income, Mortgage, and Education, and it’s the most commonly recommended method for a genuinely accurate estimate because it adds up your actual financial obligations rather than applying a flat multiplier.
Debt covers outstanding non-mortgage loans (car loans, credit cards, student loans) plus estimated funeral and final expenses, which commonly run several thousand dollars and are easy to forget.
Income is your annual income multiplied by the number of years you want that income replaced for your dependents — commonly until the youngest child would reach adulthood, or until a spouse’s expected retirement.
Mortgage is simply your remaining mortgage balance, ensuring your family could pay off the home rather than being forced to sell or downsize.
Education is the same per-child college estimate used in method two.
Add all four together, and you have a coverage target grounded in your actual obligations rather than a generic multiplier — for many families this DIME total ends up somewhat higher than the simple 10x estimate, precisely because it captures the mortgage balance that the simpler rules skip entirely.
Answering how much life insurance do you need gets easier once you run the DIME method with your own real numbers.
Subtracting What You Already Have
Every method above calculates your total obligation, but the number you actually need to buy in new coverage is that total minus what you already have available.
Subtract liquid savings and investments that could realistically be used to cover these costs, any existing life insurance (including employer-provided group coverage, which is often only one to two times your salary and rarely enough on its own), and any other assets your family could reasonably draw on.
A household with $150,000 in obligations calculated under DIME and $50,000 in existing savings and coverage would realistically need to shop for closer to $100,000 in new coverage, not the full $150,000 — a distinction that matters because over-insuring means paying unnecessarily high premiums for coverage you don’t need.
Financial advisors are asked how much life insurance do you need constantly, and the honest answer is always “it depends on your household.”
A Full Worked Example
Concrete numbers make DIME easier to actually use. Take a hypothetical household: $70,000 annual income, a $220,000 remaining mortgage balance, $15,000 in combined car loan and credit card debt, and two young children. Debt: $15,000 in loans plus roughly $10,000 in estimated final expenses, totaling $25,000. Income: replacing $70,000 a year for 15 years (until the youngest child is grown) comes to $1,050,000.
Mortgage: the $220,000 balance. Education: $100,000 per child for two kids, or $200,000.
Adding these four categories together gives a total obligation of roughly $1,495,000. If this household has $95,000 in existing savings and investments plus a $100,000 employer group policy, subtracting that $195,000 from the total brings the actual new-coverage target down to roughly $1,300,000. That’s a very different, far more defensible number than a flat 10x-income estimate of $700,000 would have produced for the same household — and it’s the mortgage and education categories specifically that account for most of the gap.
Revisiting how much life insurance do you need after a major life event keeps your coverage matched to your actual obligations.
Riders and Add-Ons Worth Knowing About
Beyond the base death benefit, most insurers offer optional riders that can be added to a term or whole life policy for an additional cost, and a few are worth understanding even if you don’t ultimately choose them. A waiver-of-premium rider keeps your policy active without requiring premium payments if you become disabled and can’t work, which protects against losing coverage exactly when your family might need it most.
An accelerated death benefit rider (increasingly included by default on many policies at no extra cost) allows you to access a portion of the death benefit early if you’re diagnosed with a qualifying terminal illness.
A child term rider adds a small amount of coverage on your children under the same policy, which is inexpensive and sometimes convenient, though it’s not a substitute for the children eventually getting their own coverage as adults if needed. None of these are essential for every buyer, but asking what’s available and what each costs is a reasonable part of comparing quotes rather than only comparing the base premium.
The short way to answer how much life insurance do you need is total obligations minus existing savings and coverage.
When to Re-Check Your Coverage Amount
The number you calculate today shouldn’t be treated as permanent — several common life events are natural triggers to redo the math. Having a child changes both the income-replacement years and adds a new education line to any DIME calculation. Buying a home, or paying down a significant chunk of an existing mortgage, changes the mortgage line directly.
A significant raise or career change shifts the income-replacement calculation proportionally. And a major change in savings — a large windfall, or conversely taking on significant new debt — shifts what you should subtract from the total obligation. Many financial advisors suggest revisiting your coverage amount roughly every few years, or immediately after any of these specific events, rather than setting a policy once in your twenties or thirties and assuming it stays adequate for decades without adjustment.
Term vs Whole Life: Which Fits Most Families
Once you have a target number, the next decision is what type of policy to buy it as. Term life insurance covers you for a fixed period (commonly 10, 20, or 30 years) and pays out only if you die during that term; it has no cash value and is significantly cheaper per dollar of coverage than whole life, which is why it’s the more commonly recommended option for most families covering a temporary need like a mortgage or child-rearing years.
Getting how much life insurance do you need right the first time saves you from both under-insuring and paying for coverage you don’t need.
Whole life insurance covers you for your entire life and builds a cash value component you can borrow against, but it costs substantially more per dollar of death benefit — often several times the premium of an equivalent term policy — and is generally recommended only for specific situations like estate planning or a permanent dependent, rather than as a default choice for straightforward income replacement.
For most people calculating “how much life insurance do you need” for the standard reason — protecting a family during working and child-rearing years — a term policy matched to the number of years you actually need the coverage (until the mortgage is paid off, or the kids are grown) is usually the more cost-effective fit.
How Age and Health Affect What You’ll Pay
Once you know how much life insurance you need, price becomes the next variable, and two factors dominate it: age and health. Term life premiums rise with age fairly predictably, which is exactly why financial advisors commonly suggest locking in a term policy earlier rather than waiting, since the same coverage amount costs meaningfully less at 30 than at 45.
Health matters just as much — most individual policies require a medical exam or health questionnaire, and factors like smoking status, chronic conditions, and family health history can significantly change your quoted rate, sometimes by multiples rather than small percentages.
Because pricing varies so much insurer to insurer for the exact same coverage amount and health profile, getting quotes from several companies (directly or through an independent broker who can compare multiple insurers at once) is worth the extra time even after you’ve settled on your target coverage number using the formulas above.
Who Actually Needs Life Insurance
Not everyone does, and it’s worth being honest about that rather than treating life insurance as universally necessary. If anyone depends on your income or your unpaid labor (a stay-at-home parent’s childcare and household contributions have real replacement value, even without a paycheck), life insurance is worth having.
If you’re single with no dependents and no debt anyone else would inherit, the case is much weaker, beyond enough to cover your own final expenses so they don’t fall on family. Stay-at-home parents in particular are commonly under-insured or skipped entirely because they don’t have a salary to plug into the 10x formula — but the cost of replacing their childcare, household management, and related labor is real and substantial, and is worth estimating explicitly rather than assuming a non-earning spouse doesn’t need coverage.
Common Mistakes People Make Estimating Their Coverage
The most common mistake is relying solely on employer-provided group life insurance, which is typically capped at one to two times salary — meaningful, but rarely enough on its own to fully replace lost income for a family, and it typically ends when you leave that job, which is a coverage gap many people don’t discover until it’s too late to fix quickly.
A second common mistake is buying a policy term that doesn’t match the actual need — a 10-year term policy bought at 30 with a newborn will expire well before that child reaches adulthood, leaving a gap right when it might still be needed.
People also frequently forget to include funeral and final expenses in their calculation, which commonly run several thousand dollars and are an unpleasant surprise for a family already dealing with the loss. Finally, some people significantly over-insure relative to their actual obligations out of general anxiety, paying for far more coverage than the math above actually supports — running one of these formulas explicitly, rather than picking a round number that feels protective, avoids both the under- and over-insuring mistakes.
Frequently Asked Questions
How much life insurance do you need if you’re single with no kids? Often much less than the standard formulas suggest — enough to cover your own debts and final expenses is a reasonable baseline if no one else depends on your income, though this changes quickly if your situation changes.
Does a stay-at-home parent need life insurance? Yes, generally — their unpaid labor (childcare, household management) has real, substantial replacement value even without a salary, and losing that support unexpectedly creates real costs for the surviving parent.
Is employer-provided life insurance enough on its own? Usually not — group coverage through an employer is commonly capped at one to two times salary and typically ends when you leave the job, so most financial advisors recommend supplementing it with an individual policy sized to your actual DIME or income-multiple calculation.
How much does term life insurance actually cost? It varies significantly by age, health, coverage amount, and term length, but term life is generally the most affordable type of life insurance per dollar of coverage — getting quotes from a few insurers for your specific numbers is the only way to know your actual cost.
What term length should I choose? Match the term to how long the underlying need actually lasts — a 20-year term to cover the years until your youngest child is expected to be financially independent, or a term matched to your remaining mortgage payoff timeline, rather than defaulting to whatever length happens to be cheapest.
Can I have more than one life insurance policy? Yes — many people layer a smaller employer group policy with an individual term policy, or combine two term policies of different lengths (a longer one covering a mortgage, a shorter one covering child-rearing years) to match coverage more precisely to when the need actually tapers off.
To close the loop on how much life insurance do you need: run DIME, subtract what you already have, and match the term length to the actual need.
Bottom Line
There’s no single universal answer to how much life insurance you need, but running the DIME method — adding up debt, income replacement, mortgage balance, and education costs, then subtracting existing savings and coverage — gives most families a defensible, personalized target rather than a generic guess.
Pair that number with a term policy matched to how many years you actually need the coverage, and you’ll typically land on meaningfully better protection for meaningfully less premium than either under-insuring on employer coverage alone or over-insuring with a policy sized to anxiety rather than arithmetic.
One more reminder on how much life insurance do you need: revisit the number after any major life event rather than setting it once and forgetting it.
Related Reading
National Association of Insurance Commissioners • Consumer Financial Protection Bureau • About BizShieldGuide
This article is for general educational purposes and does not constitute personalized financial or insurance advice. Life insurance needs vary by individual circumstances; consider speaking with a licensed insurance agent or financial advisor before purchasing a policy.

About the Author: BizShieldGuide Team
The BizShieldGuide team researches and writes plain-language guides to business and personal insurance — general liability, professional liability, workers' compensation, business owners policies, cyber liability, and industry-specific coverage for small business owners, alongside straightforward explainers on auto, home, and renters insurance for everyday readers. Our articles are grounded in publicly available data from insurers and carriers (Insureon, The Hartford, Progressive, State Farm, and others), industry cost surveys, and standard policy language, and we link to primary sources wherever a number or coverage detail could change. We are not licensed insurance agents or brokers, and nothing here replaces a quote or advice from one for your specific situation.